Home Blog Page 2

Sri Lanka FinTech Festival 2026 Kicks Off with Port City Colombo Dialogue

0

Sri Lanka FinTech Festival 2026 Kicks Off with Port City Colombo Dialogue

Opening and Organisers

  • The Sri Lanka FinTech Festival 2026 began on 2 November 2026 with a high-level dialogue at Port City Colombo.
  • The festival is powered by Visa and organised by FinTech Forum Sri Lanka, in collaboration with the Ministry of Digital Economy.
  • The Colombo Port City Economic Commission and relevant industry stakeholders took part in the discussion.

Focus of the Dialogue

  • Participants worked toward a shared vision for advancing Sri Lanka’s FinTech sector.
  • Port City Colombo was positioned as a strategic platform for FinTech growth.

Who Attended

  • International and local FinTech professionals
  • Policymakers
  • Capital-market representatives
  • Investment facilitators

Port City’s Appeal to FinTech Businesses

  • Participants recognised its potential to attract regional and international FinTech firms seeking to diversify their geographical and operational presence.
  • Key advantages identified:
    • An investor-oriented regulatory framework
    • A strategic location
    • Modern infrastructure
    • Capacity to support internationally focused business operations
  • These strengths make Port City a compelling base for companies looking to expand into South Asian and global markets.

Two-Year Roadmap

  • The discussions stressed the need for an actionable two-year roadmap to accelerate FinTech development in Port City Colombo.
  • The roadmap will be developed collaboratively by:
    • The Ministry of Digital Economy
    • The Colombo Port City Economic Commission
    • Relevant industry stakeholders
  • This approach combines policy perspectives, institutional support and practical industry expertise.

Priorities Ahead

  • Identifying key priorities for the sector
  • Addressing sector-specific requirements
  • Strengthening the enabling environment for FinTech businesses to establish and expand operations in Sri Lanka

Siyapatha Finance and Toyota Lanka Sign MOU to Enhance Vehicle Leasing in Sri Lanka

Overview

  • Siyapatha Finance PLC has entered into a strategic partnership with Toyota Lanka (Private) Limited through the signing of a Memorandum of Understanding (MOU).
  • The partnership aims to deliver flexible financing solutions, enhanced customer convenience and comprehensive vehicle ownership support.
  • It combines Siyapatha Finance’s financial expertise with Toyota Lanka’s automotive leadership to make vehicle financing more accessible, convenient and flexible.
  • Both organisations aim to streamline the leasing journey and strengthen support throughout the vehicle ownership lifecycle.

MOU Signing

  • Siyapatha Finance was represented by Rajeev De Silva, Chief Operating Officer, and Hisham Ziard, Chief Marketing Officer.
  • Toyota Lanka was represented by Masaaki Kawabata, Chairman, and Manohara Atukorala, Managing Director/Chief Executive Officer.
  • The signing ceremony was attended by the senior management teams of both organisations.

Customer Benefits

  • A more streamlined and convenient leasing experience.
  • Flexible financing solutions and long-term leasing options.
  • Enhanced service delivery.
  • Comprehensive protection through trusted insurance partners.
  • Access to a range of reliable vehicles from a globally recognised automotive brand.
  • Financing and automotive services brought together through a more integrated, customer-focused approach.

Toyota Lanka’s Network and Services

  • Toyota Lanka’s islandwide network provides convenient access to vehicle sales and after-sales support.
  • Services include routine maintenance, mechanical repairs, and body and paint services.
  • These are delivered by trained technicians using Toyota Genuine Spare Parts at dedicated service facilities.
  • The capabilities help customers preserve vehicle quality, safety, reliability and long-term value.

Shared Vision

  • Both companies aim to strengthen customer relationships, promote service excellence and contribute to the sustainable development of Sri Lanka’s vehicle leasing sector.
  • They seek to support the vehicle financing industry through service innovation, convenience and trusted partnerships.

About Siyapatha Finance PLC

  • It is the largest fully owned subsidiary of the Sampath Bank Group.
  • It operates an island-wide network of 69 branches.
  • It holds a National Long-Term Rating of ‘A(lka)’ with a Stable Outlook from Fitch Ratings.
  • Over 21 years, it has supported small and medium entrepreneurial efforts and individual financial needs across the island.

Fitch Upgrades Three Bank-Supported Sri Lankan NBFIs Following Parent Bank Upgrades

Rating Actions

  • Fitch Ratings has upgraded the National Long-Term Ratings of three bank-supported non-bank financial institutions (NBFIs) after upgrading their parent banks’ ratings.
  • People’s Leasing and Finance PLC (PLC) was upgraded to ‘AA-(lka)’ from ‘A(lka)’; Outlook Stable.
  • Merchant Bank of Sri Lanka & Finance PLC (MBSL) was upgraded to ‘AA-(lka)’ from ‘A(lka)’; Outlook Stable.
  • CBC Finance PLC (CBCF) was upgraded to ‘A+(lka)’ from ‘A(lka)’; Outlook Stable.
  • The upgrades follow those of the parent banks: People’s Bank (AA+(lka)/Stable), Bank of Ceylon (AA+(lka)/Stable) and Commercial Bank of Ceylon PLC (AA(lka)/Stable), respectively.
  • They reflect Fitch’s view of the parents’ improved ability to support their subsidiaries, as set out in its 30 October 2026 action on eight Sri Lankan banks’ national ratings.
  • National scale ratings rank issuers within a single market to help local investors differentiate risk. The ‘(lka)’ identifier marks the Sri Lankan scale, which is not comparable with Fitch’s international scales or other countries’ national scales.

Key Rating Drivers

  • The ratings are driven by Fitch’s expectation of extraordinary support from the parent banks, based on their credit profiles and their ability and propensity to support.
  • Fitch believes the parents would provide support if needed, given high ownership stakes, shared branding in some cases and management oversight, which raise reputational risk if a subsidiary were to fail.
  • Ownership stakes: People’s Bank holds 75% of PLC, Bank of Ceylon holds 84.4% of MBSL and Commercial Bank holds 100% of CBCF.
  • PLC: Its longstanding and largely successful role as the People’s Bank group’s leasing arm strengthens the parent’s propensity to support. This is balanced against PLC’s significant balance-sheet size relative to its parent.
  • MBSL: It plays a more limited role in the BOC group. High growth and variable profitability have pressured regulatory capitalisation and leverage, which may weigh on the parent’s propensity to support. BOC has supported it in the past, and support is expected to remain available for growth and regulatory capital needs in the near to medium term.
  • CBCF: Its modest group role and variable performance may limit the parent’s propensity to support, although recent earnings and asset quality have improved.

Rating Sensitivities

  • Downgrade: The ratings are sensitive to changes in the parents’ credit profiles and in Fitch’s view of their ability and propensity to provide timely support. Negative action on a parent’s National Rating could lead to similar action on its subsidiary.
  • Sustained poor performance or weakened linkages with the parent could reduce its motivation to support.
  • A significant rise in a subsidiary’s balance sheet relative to its parent could constrain the parent’s capacity to support and may lead to a downgrade.
  • Upgrade: Positive action could result from improved parent bank credit profiles or a larger role and contribution by the subsidiaries within their groups.

Debt Instrument Ratings

  • The outstanding and proposed rupee-denominated subordinated debt of PLC, MBSL and CBCF is rated two notches below each entity’s National Long-Term Rating.
  • Fitch applied its Bank Rating Criteria, as it considers the prudential capital framework for Sri Lankan finance companies closer to that of banks.
  • The ratings reflect baseline notching for loss severity, given expected poor recoveries in the event of default.
  • There is no additional notching for non-performance risk, as the debentures have no going-concern loss-absorption features.
  • Any action on the entities’ National Long-Term Ratings will result in similar action on their subordinated debt ratings.

For Information purpose only, not a buy or sell recommendation.

SDB bank Introduces Dedicated Co-operative Service Counters at Selected Branches

Overview

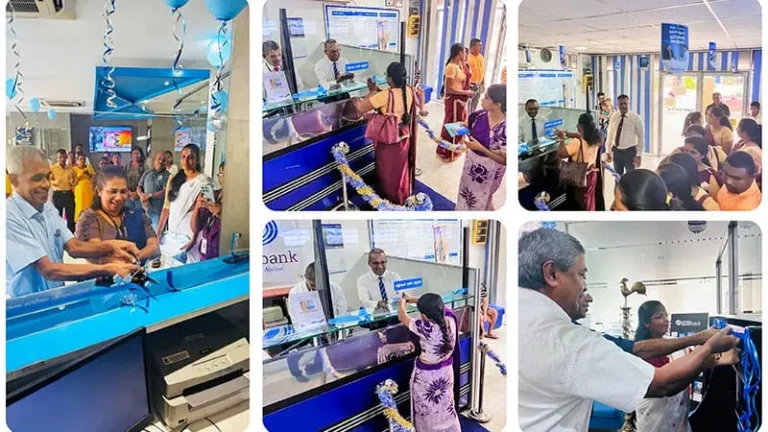
  • SDB bank has strengthened its commitment to developing Sri Lanka’s co-operative sector by introducing dedicated Co-operative Service Counters at selected branches.
  • The counters give co-operative societies and their members priority access to personalised banking services with minimal waiting time.
  • The launch is the first phase of an initiative to establish 20 dedicated counters across selected branches during 2026.
  • The bank recognises co-operative societies as a strategic customer segment and is adapting its branch services to their requirements.

Services Available

  • Deposits, withdrawals and account opening.
  • Loan information, loan applications and related banking assistance.
  • The counters serve the banking needs of both co-operative societies and their individual members.

Management Commentary

  • Lasantha Edirisuriya, Assistant General Manager, Head of Co-operative Development, said the bank’s commitment to the sector goes beyond providing financial services.
  • He said it is about understanding the needs of societies and their members and supporting the communities they serve.
  • He described the counters as a practical step towards making banking more accessible and responsive, helping customers manage everyday financial needs while building lasting relationships with the bank.

Strategic Objectives

  • The initiative supports the bank’s goals of improving operational efficiency and sustaining business growth within the co-operative sector.
  • A more focused service arrangement is intended to strengthen customer retention.
  • It also aims to create opportunities to deepen existing relationships with societies and their members.

Outlook

  • As the phased rollout progresses, the counters will give SDB bank’s focus on co-operative development a stronger presence within its branch network.
  • This connects the bank’s broader commitment to the sector with the everyday banking experience of the communities it serves.

NOTE : For Educational Purposes only, Not a buy or sell recommendation.

Bhoomi Realty Holdings Lays Foundation Stone for ‘Rozella: The Ceylon Estate’, Sri Lanka’s First Agro-Tourism Villa Project

Overview

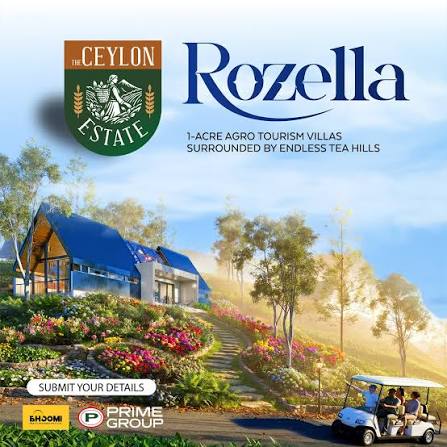
  • Bhoomi Realty Holdings, a member of Prime Group, officially laid the foundation stone for ‘Rozella: The Ceylon Estate’ on October 22, 2026.
  • It is described as Sri Lanka’s first dedicated agro-tourism villa project, marking a milestone for the country’s luxury real estate and eco-tourism sectors.
  • The development fuses world-class architectural design with the 150-year heritage of Ceylon Tea.

Location and Scale

  • The project is located in the Hatton-Rozella region, amid mist-covered mountains along the banks of the Mahaweli River.
  • It spans 22 hectares of highland landscape.
  • Development is limited to 39 eco-modern luxury villas.
  • The villas are aimed at discerning buyers, high-net-worth investors and nature enthusiasts, offering privacy and sweeping views of tea valleys.

Villa Features

  • Each estate centres on a two-bedroom eco-modern villa designed to blend with nature.
  • Floor-to-ceiling glass paneling maximises natural light and panoramic views.
  • Every villa comes with its own 1-acre private working tea plantation.
  • Each villa also includes a dedicated organic garden plot.

Investment Proposition

  • Owners can earn a secondary income through professionally managed agro-tourism villa rentals.
  • Additional passive income is expected from high-grade Ceylon tea harvests.
  • The developer promotes a dual-income model aimed at capital appreciation alongside long-term, sustainable yields.

Infrastructure and Amenities

  • The project combines sustainable luxury with state-of-the-art infrastructure, designed to ensure structural integrity.
  • Amenities include an exclusive clubhouse, walking trails and tea groves.
  • Dedicated drivers’ and servants’ quarters are also provided.

Market Positioning

  • The project aligns with global trends toward wellness-driven, nature-centric living.
  • Early investor inquiries are now officially open.

Fitch Upgrades Sri Lanka Telecom’s National Long-Term Rating to ‘AA+(lka)’ on Scale Recalibration

Rating Action

  • Fitch Ratings has revised Sri Lanka Telecom PLC’s (SLT) National Long-Term Rating to ‘AA+(lka)’ from ‘AA-(lka)’. The Outlook is Stable.
  • The change follows the recalibration of the Sri Lankan National Rating scale, which reflects shifts in relative creditworthiness among Sri Lankan issuers.
  • The recalibration came after Fitch upgraded Sri Lanka’s sovereign Long-Term Local-Currency IDR to ‘B-‘/Stable from ‘CCC+’ on 22 September 2026.
  • Fitch expects ratings of other rated corporate issuers to remain unchanged because of the recalibration; any other changes will reflect individual performance.
  • The Rating Watch Positive was resolved after the state decided not to proceed with SLT’s sale.
  • SLT’s ratings remain constrained by its parent’s weaker credit profile under Fitch’s Parent and Subsidiary Linkage and Government-Related Entities criteria.
  • SLT’s Standalone Credit Profile is stronger than the state’s, supported by its leadership in fixed telephone and broadband, second-largest mobile share, extensive optical fibre network and stronger financial profile.

Key Rating Drivers

  • Disposal plan abandoned: The plan to divest the government’s stake was formally dropped after the Supreme Court’s April 2026 ruling, which Fitch reads as a strategic shift to retain SLT as a key national asset in the digital transformation agenda.
  • Investment to support market position: SLT’s investment is expected to support the government’s commitment to guarantee minimum broadband speeds of around 2Mbps nationwide within two to three years. The government aims to grow the digital economy to USD15 billion by 2030. SLT’s financial capacity should support continued investment, including in its recently acquired 3.5GHz 5G spectrum.
  • Profitability to strengthen: Fitch forecasts the EBITDA margin to rise to 38% in 2026 (2025: 34%), driven by revenue growth and cost controls. Growth in fibre broadband and mobile subscribers and ARPU improvements should support revenue, with price adjustments helping offset cost pressures from Middle East-related tensions.
  • Interest costs to decline: Financing costs are expected to stay broadly unchanged near term, but aggressive debt settlement should lower interest costs over the medium term. Cash interest expense is forecast at LKR 5.2 billion in 2026 (2025: LKR 5.8 billion).
  • Improving sector outlook: The telecom sector is expected to see continued topline improvement from evolving data consumption after 5G rollout and the government’s digital agenda.
  • Falling leverage, rising margins: 2026 EBITDA net leverage is forecast to improve to around 0.9x for SLT and 0.4x for Dialog Axiata (from around 1.6x and 0.7x in 2025). The sector’s average EBITDA margin is expected to exceed 43% in 2026 (2025: 40%), despite rupee depreciation.

Peer Analysis

  • SLT’s rating is comparable with peers rated ‘AAA(lka)’ to ‘AA-(lka)’, including Dialog (AAA(lka)/Stable), Sunshine Holdings (AA+(lka)/Stable) and Singer (Sri Lanka) (AA-(lka)/Stable).
  • SLT is rated below Dialog mainly because of the drag from its sovereign parent’s rating.
  • Dialog controls over 60% of the mobile market and 50% of fixed broadband, and has a larger revenue base, lower forecast leverage and a better free cash flow profile. SLT’s dominance is mainly in legacy fixed telephone.
  • Sunshine is much smaller but rated equally, as its leverage and liquidity ratios are stronger and it has a stronger presence across healthcare, consumer and agriculture.
  • SLT is rated two notches above Singer. Revenues are broadly comparable, but SLT has a higher operating margin, while Singer is weighed down by its finance subsidiary and substantially higher net debt.

Key Rating-Case Assumptions

  • Revenue growth improves to 9% in 2026 (2025: 2%) and stays at a high-single-digit rate in 2027-2029.
  • Operating EBITDA margin expands to 38% in 2026 and holds at that level through 2029.
  • Effective tax rate of 30% from 2026 to 2029.
  • Capex intensity rises to 16% in 2026 (2025: 15%), then moderates to 15% from 2029 as most 5G and fibre investments are completed.
  • Dividend payout of 15% in 2026, rising to 20% of pretax profit in 2027-2029.

Rating Sensitivities

  • Downgrade: A downgrade of the sovereign’s Long-Term Local-Currency IDR could lead to a downgrade of SLT’s National Long-Term Ratings.
  • Upgrade: An upgrade of the sovereign’s Long-Term Local-Currency IDR could lead to an upgrade of SLT’s ratings.
  • The source text also states that a weakening of links between SLT and the sovereign could result in an upgrade, though it is listed under the downgrade factors.

Liquidity and Debt Structure

  • Unrestricted cash stood at LKR 19 billion at end-June 2026, including LKR 7 billion of fixed deposits, which covers LKR 10 billion of short-term borrowings maturing within 12 months.
  • SLT is likely to depend on refinancing to roll over its long-term debt.
  • Access to local banks is expected to remain solid, and the funding mix should gradually normalise as inflation moderates.

Issuer Profile

  • SLT is an integrated telecom company with a market-leading position in fixed-voice and broadband, the second-largest position in mobile and a dominant presence in digital TV.

NOTE : For Educational Purposes only, Not a buy or sell recommendation.
EPF Reaches 10% Shareholding in Both Voting and Non-Voting Shares of Tokyo Cement

  • A regulatory filing submitted to the Colombo Stock Exchange (CSE) shows that Sri Lanka’s Employees’ Provident Fund (EPF) has reached a 10% shareholding in both the voting and non-voting share classes of Tokyo Cement Company (Lanka) PLC.
  • The disclosure was submitted on November 3, 2026.
  • The shares were acquired in stages through secondary market transactions, in line with Appendix 8A of the Listing Rules.
  • The fund expanded its non-voting position first, before increasing its exposure to voting shares.

Non-Voting Shares

  • As of December 31, 2025, the EPF held 6,207,876 non-voting shares, representing 4.22% of the total issued non-voting stock.
  • By March 31, 2026, market purchases had lifted the holding to 14,701,500 non-voting shares.
  • This brought the EPF to the 10% threshold of issued non-voting equity.

Voting Shares

  • On March 31, 2026, the EPF held 22,879,611 voting shares, accounting for 7.78% of total issued voting stock.
  • Further accumulation through June 30, 2026, raised the holding to 29,403,000 voting shares.
  • This brought the fund’s voting stake to exactly 10%.

Outcome

  • Through this sequence of secondary market purchases, the EPF has attained an identical 10% shareholding in both equity classes listed under the ticker TKYO.

Inland Revenue Department Defers Mandatory TIN Certificate Requirement to April 1, 2027

0

The Inland Revenue Department has officially announced a deferral of the mandatory Taxpayer Identification Number (TIN) Certificate submission requirement.

  • The new effective date is April 1, 2027.
  • The requirement was originally due to take effect on November 1, 2026.
  • It applies to individuals participating in eight specified transactions under Circular No. SEC/PN/IT/2026/05, dated September 22, 2026.
  • The mandate was enacted under subsection (6) of Section 103 of the Inland Revenue Act, No. 24 of 2017, as amended by the Inland Revenue (Amendment) Act, No. 11 of 2026.
  • The delay was approved by the Ministry of Finance following a significant surge in demand for TIN certificates from both the general public and transaction participants.
  • During the extended transition period, the department will roll out alternative and more convenient issuance mechanisms for individuals who are already registered.
  • Individuals who have not yet obtained a TIN are encouraged to complete their registration through the department’s online e-Services platform.
  • The public notice (Ref: SEC/PN/IT/2026/06) was authorized by the Commissioner General of Inland Revenue.

JAT Holdings Posts 36% Revenue Growth in First Half, Profit After Tax Up 27%

  • JAT Holdings PLC recorded Group revenue of LKR 7.01 billion, up 36% year-on-year, supported by growth across local businesses and a higher contribution from international operations.
  • Local revenue rose 14% to LKR 4.56 billion, primarily supported by the emulsion category.
  • Foreign operations revenue increased 115% to LKR 2.45 billion, reflecting improving business conditions in Bangladesh and an expanding international presence.
  • Gross profit margin across foreign markets improved from 24% to 26%.
  • Gross profit rose 36% to LKR 2.46 billion, maintaining a 35% margin despite higher raw material import costs and rising fuel prices.
  • Operating profit increased 15% to LKR 653 million, while operating margin moderated from 11% to 9%.
  • The margin dip reflects higher administrative, selling and distribution expenses, including consolidation of the Mirotone operation, Volt software amortisation, transportation and expanded storage capacity.
  • Favourable exchange rate movements helped reduce finance costs.
  • Profit before tax grew 27% to LKR 602 million, and profit after tax rose 27% to LKR 504 million.

Management Commentary

  • CEO Nishal Ferdinando said the first-half performance reflects the increasing breadth of the Group’s growth, with stronger contributions from both local and international operations.
  • He noted that maintaining gross margin amid higher input costs reinforces the value of investments in manufacturing efficiency and backward vertical integration.
  • The focus for the second half is on translating the broader operating base into sustained profitability and long-term growth.
  • Managing Director Aelian Gunawardene said progress across Bangladesh, New Zealand and Australia reflects the growing scale of JAT’s international platform.
  • He added that the long-term ambition is to build a stronger Sri Lankan multinational able to compete sustainably across regional and international markets.

Local Business Performance

  • Wood coatings: Market share expanded to 57.1%, with 2% revenue growth and a 1.6% improvement in net gross profit margin, aided by the second phase of the Acrylic Binder Plant upgrade.
  • The loyalty customer base grew 7% to exceed 191,000, contributing around 78% to 80% of sales.
  • Decorative paints: Revenue grew 107%, driven by brands including White by JAT, Hydro Plus and Wallz, with segment gross margin improving by 1.4%.
  • JAT HeatBlock20 was introduced to the industrial market.
  • Brushes and Rollers: Retained market leadership with a 31% share and 11% revenue growth.
  • Furnishing: Grew 16%, supported by a confirmed project pipeline of LKR 561 million.

Manufacturing Integration

  • The upgraded Acrylic Binder Plant in Sri Lanka and the start of alkyd resin exports from Bangladesh to Sri Lanka strengthened backward vertical integration.
  • This supports greater manufacturing control and a more resilient regional supply platform.

Volt Charge

  • Invoiced 2,000 L2 chargers to John Keells CG Auto for BYD vehicles.
  • Completed engineering of a 200 kW commercial vehicle charger.
  • Volt app user base rose to 25,000 active users.
  • Revenue declined 5% due to the timing of revenue recognition.
  • Commenced a pilot project for electric two- and three-wheeler charging, with the first charger installed in Kottawa.

International Operations

  • Bangladesh: Industrial sales grew 26%, retail sales 42% and CoatEX revenue 151%.
  • Mirotone New Zealand: Month-on-month sales rose 12% in August and 9% in September, following slower movement in Q1.
  • The business reported a first-half loss of NZD 99,000 amid challenging market conditions.
  • Initial sales to Fiji were recorded, an early step in expanding export reach from New Zealand.
  • Mirotone Australia: Local facility and colour-matching infrastructure are now fully established.
  • Product R&D and market testing progressed, with initial shipments supporting product familiarisation and commercial discussions.

Corporate Profile

  • JAT Holdings holds a Fitch National Long-Term Rating of AA (lka).
  • The Group has a presence across 11 markets.

NOTE : For Educational Purposes only, Not a buy or sell recommendation.
CSE Extends Rally for Second Day as ASPI Crosses 21,000 Mark

0
  • The Colombo Stock Exchange (CSE) recorded a strong rally for the second consecutive day, driven by substantial gains across key market indices.
  • The All Share Price Index (ASPI) climbed by 589.18 points (2.87%) today (November 5), surpassing the 21,000-point milestone.
  • The ASPI ended the trading session at 21,130.30 points.
  • This follows a sharp increase of 421.48 points yesterday (November 4).
  • The index’s total two-day surge stands at 1,010.66 points, significantly boosting investor sentiment.
  • The blue-chip S&P SL20 index also showed strong momentum, rising by 194.79 points.
  • The S&P SL20 crossed the 6,000 threshold and closed at 6,029.88 points.
  • Trading activity remained strong, with total market turnover at Rs. 5.43 billion for the day.

NOTE : For educational purposed only, not a buy or sell recommendation